All Categories
Featured
Economists suggest that anybody thinking about credit card financial obligation forgiveness first evaluate their financial situation, interact directly with their financial institution or a respectable counseling service, and understand both the short-term and long-term effects. With mindful preparation and confirmation, eligible Americans can take advantage of these programs in 2026 to minimize monetary stress and pursue long-term monetary stability.
Debt Relief vs. Management: Choosing 2026 Strategies
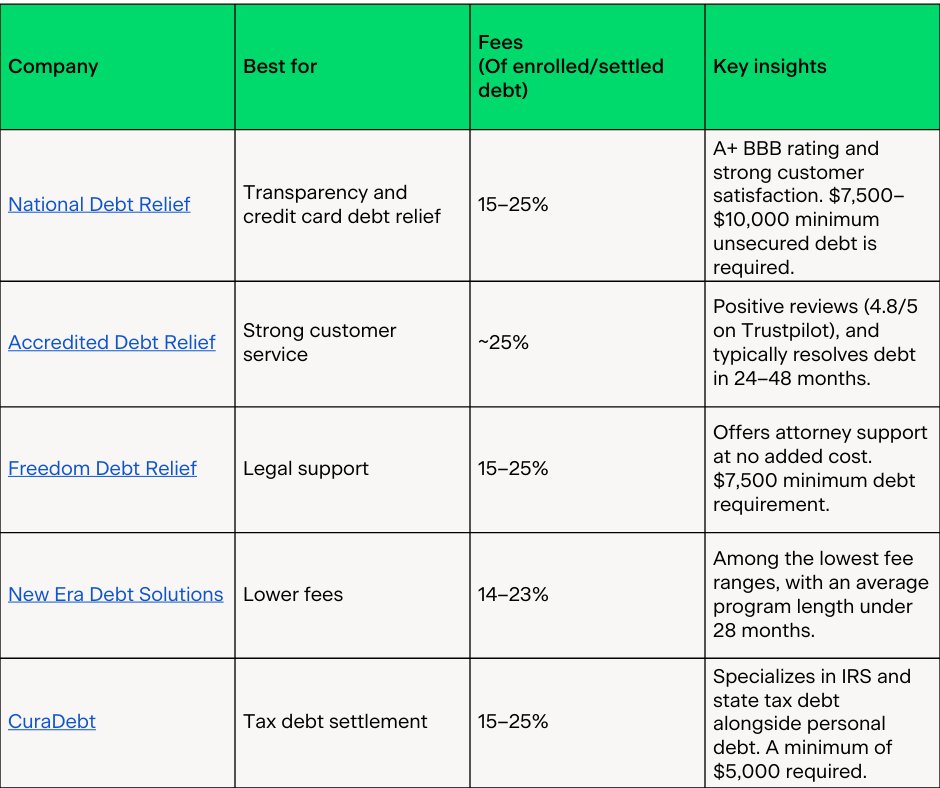
Here are the genuine financial obligation relief programs that rank highestand how to decide in between settlement and credit therapy. Not all financial obligation relief programs fit all scenarios. Here's how to inform which one matches your challenge level: Debt combination loanNonePay 100%, better termsGood credit, consistent earnings, just need to simplifyCredit therapy (DMP)Mild/ModeratePay 100%, lower interestCurrent on payments, can afford decreased ratesDebt settlementSignificantPay less than 100%Already behind, can't afford minimumsBankruptcySevereLegal discharge/restructureOverwhelmed, lenders suing, no other choice You're already behind on payments by 90+ daysYou can't pay for minimum payments even with lower interestYou're dealing with substantial financial difficulty (task loss, medical emergency, divorce)Your credit is already damaged from missed paymentsYou can save $200-$500/month towards settlements You're existing on payments or only somewhat behindYou have steady earnings to cover a regular monthly paymentYou desire to avoid major credit damageYou can pay for to pay back 100% if interest is loweredYou require 3-5 years to pay off debt Ask yourself: Can I afford my minimum payments if interest rates were cut to 0-8%?

Latest Posts
Comprehensive Debt Relief Reviews to Watch
Finding Financial Hardship Help in 2026
Objective Evaluations of Top Management Strategies